Business Insurance is a segment that keeps growing every year, and if you are considering insurance as a career or side-income opportunity in 2026, it is worth exploring. India’s commercial insurance market is valued at around ₹3.29 lakh crore (US$37.82 billion) in 2024 and projected to reach ₹7.05 lakh crore (US$81.04 billion) by 2033, growing at roughly 8.13% a year, covering everything from liability and property to group health and marine insurance for businesses. This creates an ongoing need for business POSP advisors who can help customers understand, compare, and purchase appropriate insurance.
Can I Become a Business Insurance POSP Insurance Advisor?
A POSP model can offer a relatively accessible entry into this market, provided you complete the applicable training, examination and onboarding requirements of the insurer or intermediary you work with.
Want to become a certified business insurance POSP advisor?
You can explore an opportunity with Probus Insurance and understand the onboarding process, insurance products and support available to advisors. The right platform can matter as much as certification, because your ability to compare policies, access insurers, service customers and manage renewals can directly affect your ability to build a sustainable insurance business.
Who Is a POSP Insurance Advisor?
POSP means Point of Sales Person. A POSP insurance advisor is an individual who has completed the prescribed requirements and is authorised through an insurer or insurance intermediary to solicit and market specified insurance products.
For someone interested in business insurance, this can mean helping customers understand available corporate insurance plans options, premiums, coverage and policy terms, and assisting with the purchase process.
POSP vs Insurance Agent
A POSP isn’t just another name for a traditional insurance agent. The regulatory framework, products that can be sold, training, and appointment arrangements can differ. IRDAI has specific frameworks for Point of Sales Persons, including for both life and non-life insurance.
What Should You Know Before Becoming an Insurance Agent?
Before choosing this career, understand that insurance sales is not simply about finding customers and collecting commissions.
A POSP insurance advisor role involves trust
Customers expect you to explain premiums, coverage, exclusions and claims processes clearly. Your reputation can determine whether one customer becomes ten through referrals.
Income depends on your own effort
A POSP generally earns through commissions or remuneration linked to business generated, but earnings vary by product, insurer arrangement, policy volume, renewals and applicable commission structures. IRDAI requires insurers to have board-approved commission policies, so there is no universal fixed POSP commission applicable to every platform.
How to Get Started as a Business Insurance Agent?
If your objective is specifically to sell business insurance, start by choosing an insurer or insurance intermediary that onboards POSPs.
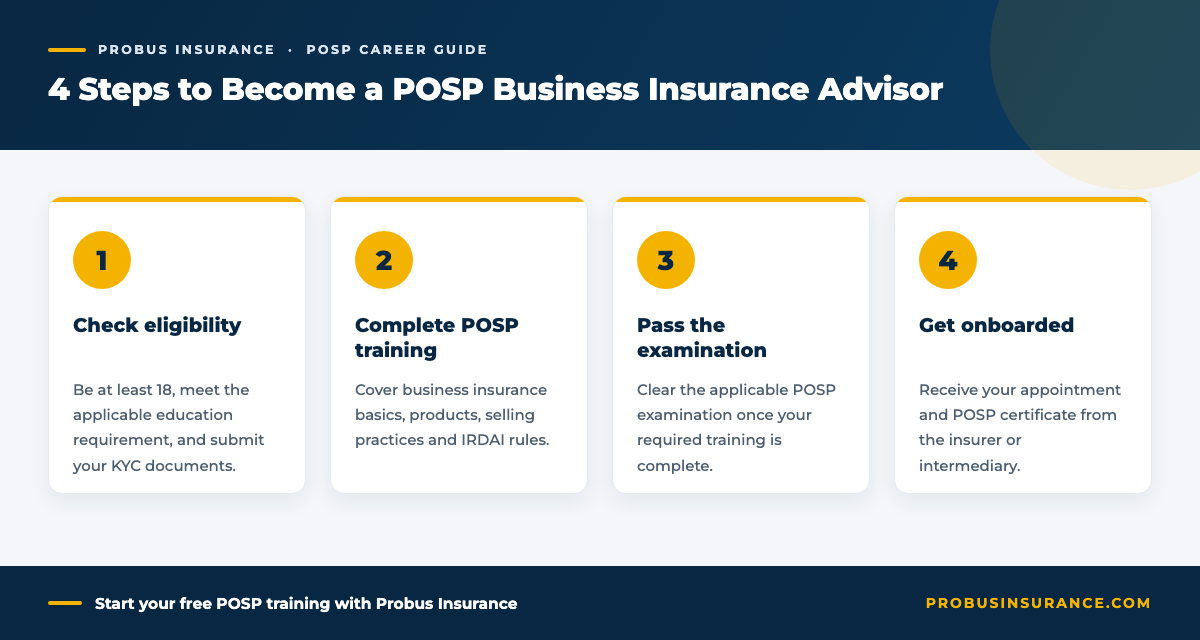
Step 1: Check eligibility
Common requirements include being at least 18 years old, meeting the applicable educational requirement, and submitting KYC documents. Requirements can vary according to the applicable regulatory framework and onboarding organisation.
Step 2: Complete training as a POSP insurance advisor
POSP training covers business insurance basics, products, selling practices, customer protection and regulatory requirements. IRDAI’s POSP framework includes defined training and examination requirements.
Step 3: Pass the examination
After completing the required training, you must pass the applicable POSP examination before appointment or certification.
Step 4: Get onboarded
The insurer or intermediary issues the applicable appointment and POSP certificate or identification required under its onboarding process.
[Alt: Infographic showing the four steps to become a POSP business insurance advisor with Probus] | infographic-1-4-steps-business-posp.png
Is Becoming an Insurance Agent a Good Career Path?
It can be, particularly for people who are comfortable with sales, networking, and customer relationships.
Why business insurance can be attractive
India’s small and medium enterprise segment remains significantly underinsured relative to the risks these businesses actually carry, from fire and liability to employee health cover. Business insurance relationships also tend to be higher value and multi-year, since a single business client can need several policies at once, such as group mediclaim, group term life and property cover.
Remember this is not passive income
Selling to businesses generally takes longer than individual retail sales, since owners want to understand liability exposure, coverage limits and pricing across multiple policies before committing. It rewards advisors who invest in ongoing relationship management, not one-off transactions.
What Are the Requirements to Become a POSP Business Insurance Advisor?
The exact requirements should always be confirmed with the organisation onboarding you, because regulatory requirements can change.
Typical eligibility
- Age: 18 years or above
- Education: Applicable minimum educational qualification
- Identity: PAN and Aadhaar
- Address: Valid address proof
- Banking: Bank account details or a cancelled cheque where required
- Training: Prescribed POSP training
- Examination: Required examination and successful completion
- Appointment: Formal onboarding by the insurer or intermediary
Business insurance often spans general, health and life POSP categories depending on which corporate products you sell, such as group mediclaim or group term insurance. Confirm current requirements with your onboarding organisation before advising business clients. The Insurance Regulatory and Development Authority of India (IRDAI) regulates this segment, setting rules that help ensure fair pricing and protect customers.
Can You Become an Insurance Agent Without Experience?
Yes, prior insurance-sales experience is not necessarily required to enter the POSP route.
What matters more than experience?
- Communication. You need to explain insurance without confusing the customer.
- Learning ability. Every insurance category has its own terminology and coverage conditions that you must understand.
- Relationship building. Existing contacts can help generate your first customers.
- Digital skills. WhatsApp, email, online quotations and digital policy processes are increasingly important.
Read on: Who is Eligible to be a PoSP?
How Do Insurance Agents Find and Keep Clients?
Getting your first customer can feel like the hardest part of becoming an insurance advisor. But you may already have a useful starting point. The people around you can help you build your first network. From there, the goal is not just to sell a single policy. It is to create relationships that bring renewals, referrals and repeat business.
Start with your existing network
Friends, relatives, former colleagues, neighbours, local business owners and professional contacts can all become potential leads. You can start a simple conversation about their business insurance needs rather than immediately trying to sell a policy. The important thing is to avoid aggressive selling. Your first goal should be building trust, not closing every conversation.
Build a renewal or repeat-purchase pipeline
Selling the policy is only the beginning. A good insurance advisor thinks about what happens next. Keep track of renewal or repurchase timing and contact customers before their policies expire. Over time, this can become an important part of your business, since you are working with people who already know and trust you.
Earn referrals through good service
Customers usually recommend an advisor not because a policy was sold to them, but because the process was easy. Respond when they have questions, explain coverage in simple terms, and be transparent about exclusions. For a new POSP insurance advisor, this is one of the most valuable ways to grow: sell well, service well, and let satisfied customers help build your network.
What’s the Earning Potential for a Business Insurance Agent?
There is no single guaranteed income figure for a POSP insurance advisor.
What determines your earnings?
- Number of policies sold
- Premium generated
- Product mix
- Commission or remuneration structure
- Renewal business
- Customer retention
- Referrals
- Insurer or intermediary arrangement
Don’t choose a platform only by commission
A higher headline payout may not necessarily create higher long-term income. Lead support, insurer choice, digital tools, claims assistance, training and renewal support can be equally important. IRDAI’s regulatory framework requires commission structures to be governed through the applicable insurer’s board-approved policy rather than a universal commission percentage.
How Long Does It Take to Become a Licensed Insurance Agent?
The timeline depends on the route you choose and the onboarding organisation.
POSP route
The process generally involves eligibility, KYC, training, examination, certification or appointment, then sales. The regulatory framework includes training and examination requirements, with the precise current process depending on the category of insurance and organisation.
Traditional insurance agency route
A traditional insurance agent may follow a different regulatory and appointment process. You can read more about the difference in this advisor licensing guide. Do not assume that POSP certification and traditional agent licensing are interchangeable.
POSP or Traditional Insurance Agent: Which Is Better?
POSP can suit you if
You want a relatively accessible entry into insurance sales, flexibility, and the ability to focus on permitted products through an insurer or intermediary.
Traditional agency can suit you if
You want to build a longer-term insurance advisory business under the applicable agency structure and are prepared for its specific licensing and regulatory requirements. The right choice depends on your career goals, product focus, sales model and the organisation you join.
Which Insurance Products Can a POSP Sell?
A POSP cannot automatically sell every insurance product simply because they have completed certification.
Product eligibility matters
IRDAI has issued specific lists and guidelines concerning products that may be marketed through Point of Sales Persons. For someone entering through business insurance, confirm exactly which products and covers you are permitted to market through your onboarding organisation, and cross-check them against advisor recruitment and career support.
What Skills Are Needed to Be a POSP?
Becoming a POSP is not only about completing the required training and certification. To build a successful career, you also need to know how to talk to customers, understand their needs, explain insurance clearly and stay connected after the sale.
Communication
Insurance can sound complicated to customers, and business insurance has its own share of unfamiliar terms. A good POSP insurance advisor should be able to explain these terms in simple language and listen carefully before recommending a policy.
Sales
Being an insurance advisor involves sales, but good selling is not about pushing the most expensive policy. It starts with understanding the customer’s situation and helping them make an informed decision, not simply closing the sale.
Product knowledge
This is one of the most important skills for a POSP. You should understand the basics of corporate insurance plans, including:
- Liability insurance: protects a business against legal claims arising from injury, damage or negligence.
- Group mediclaim: health cover extended to a business’s employees under a single group policy.
- Group term insurance: life cover extended to employees, often used as part of an employee benefits package.
- Property or fire insurance: protects business premises, equipment and stock against fire and allied perils.
- Marine or cargo insurance: covers goods in transit, relevant for businesses involved in trading or logistics.
Customers will often ask pointed questions about these terms, and you should be able to answer clearly and honestly.
Follow-up
Selling the policy is not the end of the relationship. Most business insurance products create an opportunity to stay connected with customers, whether through renewal reminders or periodic check-ins. Consistent follow-up can help you build renewals, repeat customers, and referrals over time.
Digital skills
A modern POSP insurance advisor should be comfortable working digitally, using online tools for generating quotations, comparing policies, sharing information and managing renewal reminders. You do not need to be a technology expert, but you should be comfortable using smartphones, email, messaging platforms, and online insurance systems.
Can POSP Business Insurance Be a Side Income?
For some people, yes.
Why it can work
A POSP model can be attractive to people who already have a network, work in finance, run a local business, or have strong community connections. It can offer a flexible route to additional income alongside an existing job or routine, provided you commit real time to it.
What it should not be
It should not be marketed as guaranteed passive income. Building meaningful earnings requires customers, trust, product knowledge and ongoing service. Want to check this in more detail: Can I Do POSP Part Time?
How Can Probus Insurance Help You Start?
If you are researching how to become a POSP insurance advisor, choosing the right insurance intermediary is an important part of the decision. Probus Insurance can be explored for its insurance ecosystem and available services. Beyond business insurance, prospective advisors should look at the broader range of insurance products, customer support, digital processes and policy comparison capabilities across the platform.
A platform should ideally help you become more than someone who simply sells a policy. The long-term opportunity is to become a trusted insurance advisor who can help customers make informed decisions.
Conclusion
Becoming a POSP insurance advisor can be a practical way to enter India’s insurance distribution industry, particularly if your interest is business insurance. Valued at around ₹3.29 lakh crore (US$37.82 billion) in 2024 and projected to reach ₹7.05 lakh crore (US$81.04 billion) by 2033, growing at roughly 8.13% a year, covering everything from liability and property to group health and marine insurance for businesses.
But certification alone will not create a career. Your long-term success will depend on product knowledge, ethical selling, customer relationships, renewals and referrals. If you are ready to explore the opportunity, research the current POSP requirements and compare the support offered by insurance intermediaries such as Probus Insurance before choosing where to start.