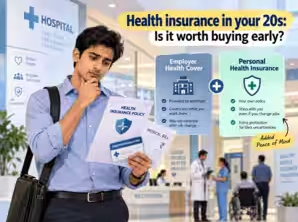
Being young, healthy and covered by your employer can make buying a separate health insurance policy seem unnecessary.
But employer cover can stop if you leave the organisation. A job change, layoff, sabbatical or move into entrepreneurship could therefore leave you without the same level of health protection.
An unexpected accident, hospitalisation or illness can also result in a hefty medical bill that may not be fully covered by your corporate medical insurance.
So, does it make sense to buy a separate health insurance in your 20s, even when you already have employer cover?
Why buying health insurance while you are young can be beneficial
Health risks can arise at any age, which is one reason young professionals may want to consider securing their own health cover early.
“Many early-onset conditions have a stronger genetic link or inherited risk factors. Further, one can also meet with serious accidents causing injuries which require surgery and hospitalisation,” says Hari Radhakrishnan, Expert, Insurance Brokers Association of India (IBAI).
There is also a financial advantage to buying a policy when you are relatively young and healthy.
“Buying your own policy at 25 or 27, while you’re healthy, can mean lower entry premiums and allows you to complete applicable waiting periods before you may need the cover. It’s really a decision made with your 35-year-old self in mind, not your 25-year-old self,” says Sarita Joshi – Head of Health and Life Insurance, Probus.